
Can You Pay Personal Expenses From Your Corporate Bank Account? Be Careful – The IRS May See It Differently.
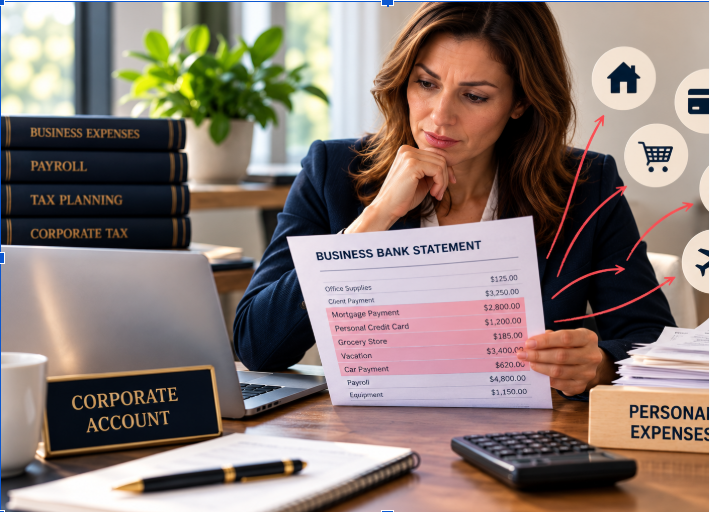
I have seen business owners treat their corporate bank accounts almost like personal checking accounts.
- Oh, I need to pay a mortgage? I have money in my corporate bank account I will do it.
- Personal credit card bill? Sure, will pay from business.
- Groceries, vacations, car payments? Same story
After all, it is YOUR corporation and YOUR money, right? You are the rightful owner, this belongs to you so why not?
Well, not exactly.
Once you operate through a corporation, the corporation is a separate legal entity. And just because you own 100% of the company does NOT mean every payment from its bank account is automatically a deductible business expense.
In fact, there is a Tax Court case that illustrates just how expensive this misunderstanding can become.
A Business Owner Who Used His Corporation’s Money for Personal Expenses
InMoacir Santos v. Commissioner, T.C. Memo. 2019-148, a taxpayer owned an engineering and paving business operating as a C corporation.
During 2010, he regularly withdrew money from the corporate bank account, transferred funds to his personal account, and used corporate funds to pay personal expenses.
He also failed to file his personal income tax return for that year.
Eventually, the IRS assessed additional taxes, and the case ended up in Tax Court.
The taxpayer argued that certain amounts belonged to the corporation and that some of the withdrawals were used for legitimate business expenses.
But the IRS had a different position.
The money taken from the corporation for the shareholder’s personal benefit should be treated as constructive dividends.
And that distinction can make a substantial difference in taxes.
What Is a Constructive Dividend?
A constructive dividend is not necessarily a dividend that the corporation formally declared or paid to its shareholders.
It can arise when a corporation provides an economic benefit to a shareholder without expecting repayment, and the payment is not otherwise properly treated as a deductible business expense or another legitimate transaction.
For example, suppose you own a C corporation and use its checking account to pay $30,000 of your personal expenses.
You may think you are simply taking money out of your own business.
But the IRS may see something else.
The corporation paid your personal expenses, and you personally benefited from those payments.
Depending on the circumstances and the corporation’s earnings and profits, the IRS may treat the paymentsas taxable dividends to you.
And here is where the problem becomes expensive.
A C corporation generally pays federal income tax on its profits. Dividends are not deductible by the corporation, and the shareholder may also owe personal income tax on those dividends.
In other words, the same corporate earnings can be taxed at both the corporate and shareholder levels.
Not exactly the tax savings the business owner had in mind.
What Happened in the Santos Case?
The IRS examined the corporation’s bank records and identified cash withdrawals, transfers and payments that appeared to benefit the shareholder personally.
The taxpayer tried to establish that some of the withdrawals were actually used to pay business expenses.
But there was a serious problem.
The documentation did not support his explanation.
The court found significant inconsistencies in the receipts he presented and questioned their authenticity.
This is something I always emphasize when working with business owners:
A business expense needs to be a legitimate business expense, and you need documentation to support it.
You cannot simply withdraw cash from your corporate account and later decide that it must have been used for business purposes.
And creating receipts or explanations after the fact is certainly not the solution.
In this case, the Tax Court concluded that the taxpayer had received$156,469 in constructive dividends.
The IRS also established that the corporation had sufficient earnings and profits for the entire amount to be treated as dividends.
The taxpayer’s failure to maintain reliable records became a very expensive problem.
But What If You Have an S Corporation?
Now, this is where I want to make an important distinction.
The Santos case involved aC corporation.
Many small businesses, however, operate asS corporations, and the tax treatment is different.
Generally, an S corporation does not pay federal income tax at the corporate level. Instead, income passes through to its shareholders.
Shareholders may take distributions, and those distributions are generally not taxable to the extent of their available stock basis, although exceptions apply.
But that does NOT mean an S corporation owner can simply pay every personal expense from the business account and call it a business deduction.
Personal expenses are still personal expenses.
If the corporation pays your mortgage, groceries or personal credit card, those payments need to be properly accounted for.
Depending on the facts, they may be treated as shareholder distributions, compensation, repayments of legitimate shareholder loans or another appropriate category.
And there is another important issue with S corporations.
Reasonable compensation.
If you work for your S corporation, the IRS generally expects you to receive reasonable W-2 compensation for the services you perform.
You cannot simply avoid payroll taxes by taking all the money out as distributions.
The IRS can reclassify distributions or other payments as wages when the circumstances support that treatment.
So although the constructive dividend rules from the Santos case primarily concern C corporations,mixing personal and corporate expenses can create problems for S corporation owners as well.
Why I Care About How Business Expenses Are Categorized
When I prepare business tax returns, I need to understand what the numbers actually represent.
If I see substantial expenses categorized as “Miscellaneous,” “Other Expenses,” or simply “Business Expenses,” I may ask for additional information.
Not because I want to make the tax preparation process more difficult.Because I need to know what we are deducting.Each expense should have a category not just general wording
A payment coming out of a corporate bank account does not automatically make it deductible.
The question is whether the expense was ordinary and necessary for the business, properly documented, and correctly classified.
For example, if a business owner pays a personal credit card from the corporate account, we need to know whether that card was used for business purchases, personal expenses, or both.
And if there are legitimate business purchases, we need the supporting records.
I would much rather ask those questions before the tax return is filed than have the taxpayer answer them during an IRS examination.
So Can You Ever Take Money Out of Your Corporation?
Of course you can.
Owning a corporation does not mean you cannot access the money you earned through your business.
ButHOW you take that money out matters.
Depending on the type of corporation and the circumstances, there are legitimate ways to receive money from your company:
- W-2 compensation for services performed.
- Properly documented shareholder distributions.
- Dividends from a C corporation.
- Repayment of legitimate loans between the shareholder and corporation.
- Reimbursement of actual business expenses under an appropriate reimbursement arrangement.
Each has different tax and reporting consequences.
And what works for one corporation may not work for another.
This is why I believe these matters should be addressed during the year, not when someone brings a box of bank statements to their CPA in March or April.
Your Corporation Is Not Your Personal Checking Account
The Santos case is a good reminder that the IRS looks at what actually happened, not simply how the taxpayer describes a transaction.
Calling something a business expense does not make it one.
And calling a payment a loan or distribution does not automatically make that classification correct either.
The records, the business purpose, the corporate structure and the actual facts all matter.
My advice to business owners is simple:
Keep your business and personal expenses separate.
If you need to take money out of your corporation, do it properly and record it correctly.
And if you have already mixed personal and business transactions, don’t ignore the problem. Review the accounts, identify the transactions and determine how they should be treated before filing the tax returns.
It is much easier to correct bookkeeping and reporting issues before the IRS starts asking questions.
_________________________________________________________________________________________________________________
This article discusses the U.S. Tax Court decision in Moacir Santos v. Commissioner, T.C. Memo. 2019-148, and general federal tax considerations for corporate shareholders. Every tax situation is different, and the proper treatment depends on the facts, corporate structure and applicable tax law.
Katerina Donckels, CPA, EA
Katerina Donckels CPA Inc.
Tax Preparation | IRS Representation | Business Accounting